Table of Contents
- Understand Your Home’s Market Value and Set the Right Price
- Make Strategic Home Improvements Before Selling
- Apply Home Staging Tips for Sellers to Attract Buyers
- Prepare Your Home for Showings and Inspections
- Decide Whether to Sell a House As Is or Make Repairs
- Work with the Right Real Estate Professional
- Evaluate Offers and Negotiate for the Best Terms
- Calculate Your Net Proceeds After Selling Costs
- Frequently Asked Questions
Last Updated: October 4, 2026
Understand Your Home’s Market Value and Set the Right Price
Setting the right price is the single most important decision when selling your home for maximum value. Price too high and buyers walk away; price too low and you leave money on the table.
Research comparable sales in your area from the last three to six months. Focus on homes with similar square footage, age, condition, and features. Check actual sale prices, not listing prices, to establish a realistic baseline.
Research comparable sales in your area
Use public records, real estate websites, and county assessor databases to find at least five to ten comparable homes.
When comparing homes, focus on these details:
- Square footage and lot size
- Number of bedrooms and bathrooms
- Age and condition of the home
- Recent updates or renovations
- Location and proximity to schools or amenities
Get a professional appraisal or market analysis
A professional appraisal or comparative market analysis (CMA) from a real estate professional provides an objective assessment using local market data and recent comparable sales.
At CT Heritage Village, Andrew Walker provides in-home market reviews and professional valuations for homeowners in the Southbury area.
Make Strategic Home Improvements Before Selling
Not all home improvements deliver the same return. Prioritize based on budget, timeline, and impact on buyer interest and sale price.
Rank improvements by impact, cost, and timeline
Rank improvements by three factors: buyer impact, cost, and time required.
Tier 1: Must-fix issues (do these first)
Deal-breakers include roof leaks, foundation cracks, failing HVAC, electrical hazards, plumbing issues, mold, and pest damage. Cost: $2,000-$15,000+. Timeline: 1-4 weeks. Fix these before listing, inspectors will find them, and you’ll lose leverage.
Tier 2: High-impact, moderate-cost improvements (do these second)
High-impact improvements include exterior paint, landscaping, interior paint, kitchen/bathroom hardware, flooring, and door refinishing. Cost: $500-$5,000 per item. Timeline: 1-2 weeks. These create strong first impressions and feel like larger upgrades to buyers.
Tier 3: Nice-to-have improvements (do these only if budget and time allow)
Nice-to-have improvements (deck upgrades, smart home features, appliance upgrades) cost $1,000-$10,000 and take 2-6 weeks. Pursue only if budget remains after Tier 1 and 2.
Tier 4: Skip these (avoid major renovations)
Skip major renovations (kitchen remodels, bathroom gut-renovations, room additions, whole-home flooring). These are too expensive and rarely recoup their cost.
Create a budget-based improvement plan
$5,000 budget: Exterior paint ($2,000), landscaping ($1,000), interior paint ($1,200), kitchen hardware ($800). $15,000 budget: Add roof repair ($4,000) and flooring ($2,500).
Avoid over-personalizing your improvements
Use neutral paint colors, classic finishes, and broad-appeal landscaping. Avoid bold colors, designer choices, and niche upgrades. Help buyers envision themselves in the space.
Time improvements to your listing date
For 30-day timelines, focus on paint, landscaping, cleaning, and minor repairs. For 8-12 weeks, tackle larger Tier 2 projects. Avoid starting major work less than 2 weeks before listing.
Apply Home Staging Tips for Sellers to Attract Buyers
Home staging helps buyers envision themselves in your space and drives offers.
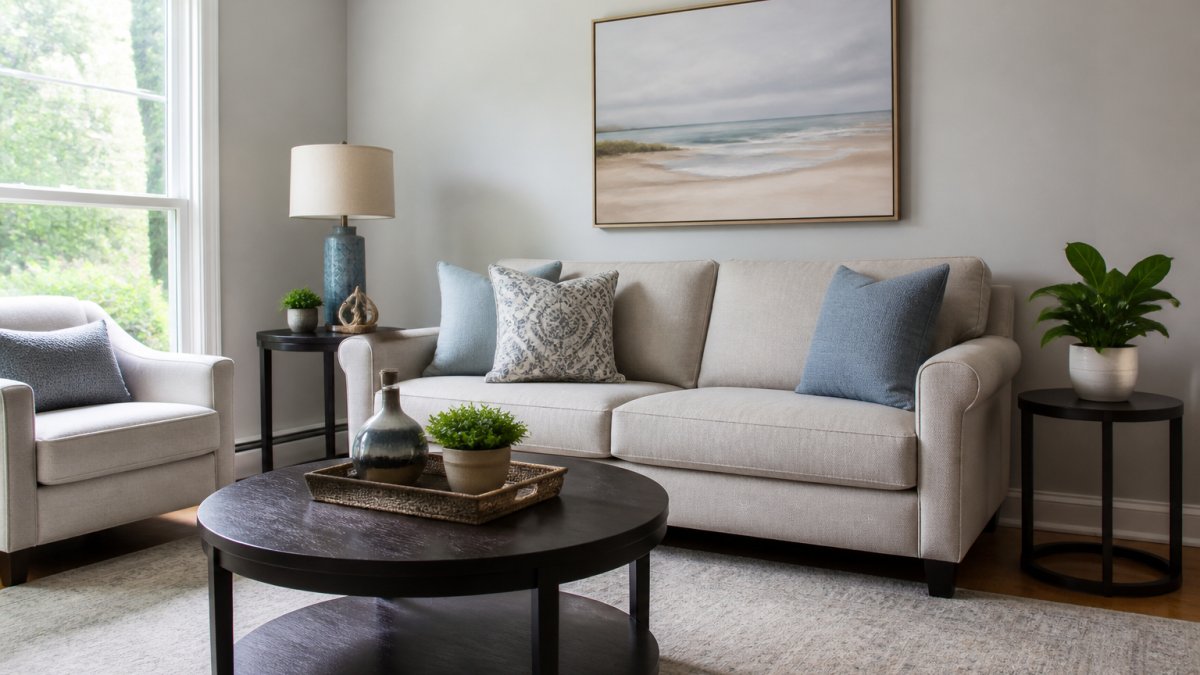
Declutter and depersonalize each room
Remove personal items, family photos, and excess furniture. Pack away 30-50% of closet items, seasonal decorations, and kitchen gadgets. Clear nightstands and bathroom counters to make rooms feel larger and help buyers envision themselves in the space.
Enhance curb appeal and first impressions
Enhance curb appeal with a refreshed front door, trimmed landscaping, colorful flowers, power-washed driveway, mowed lawn, fresh mulch, and working exterior lights. A clean exterior signals home care and builds buyer confidence.
Prepare Your Home for Showings and Inspections
Deep clean baseboards, light fixtures, windows, and grout. Service HVAC, test outlets, and fix leaky faucets. During showings, open curtains, turn on lights, and play soft music. Keep pets away and ensure the home feels peaceful and uncluttered.
Decide Whether to Sell a House As Is or Make Repairs
Selling as-is works in competitive markets with low inventory, but typically results in lower offers as buyers factor repair costs into bids. If you need quick sales and lack repair funds, as-is selling may make sense. Otherwise, strategic repairs usually generate higher final prices. Always disclose known issues honestly.
Work with the Right Real Estate Professional
A skilled real estate professional with strong local market knowledge makes a measurable difference in sale price and speed. Interview multiple professionals and ask about their marketing approach, average days-on-market, and negotiation strategy. Choose someone who provides honest feedback and focuses on maximizing your net proceeds. At CT Heritage Village, Andrew Walker brings expertise in the Southbury market and personalized strategies for sellers.
Evaluate Offers and Negotiate for the Best Terms
The highest offer price rarely equals the best offer. Buyers can sweeten deals with favorable terms that reduce your risk, accelerate closing, or lower your net proceeds loss. Learning to compare offers across multiple dimensions, not just price, is essential to maximizing your actual financial outcome.
Understand the true cost of contingencies
Contingencies are conditions the buyer can use to back out or renegotiate. Each one introduces uncertainty and extends your timeline. Common contingencies include:
- Financing contingency: Buyer’s offer depends on loan approval. If the appraisal comes in low, the buyer can renegotiate or walk. This is the most common and highest-risk contingency.
- Inspection contingency: Buyer can request repairs or credits after inspection. Expect 7-10 days for inspection and negotiation. Buyers often use this to chip away at price.
- Appraisal contingency: If the appraisal is below the offer price, the buyer can renegotiate or withdraw. This protects the lender but creates price uncertainty for you.
- Sale of current home contingency: Buyer’s offer depends on selling their existing home first. This introduces unpredictable delays and risk.
A cash offer with no contingencies is worth significantly more than a contingent offer at the same price, because you avoid renegotiation risk and close faster.
Compare offers across key financial and timing factors
Create a simple comparison table for each offer you receive:
| Factor | Offer A | Offer B | Offer C |
|---|---|---|---|
| Offer price | $425,000 | $420,000 | $415,000 |
| Down payment % | 10% | 20% | 100% (cash) |
| Financing contingency | Yes | Yes | No |
| Inspection contingency | Yes | Yes | No |
| Appraisal contingency | Yes | No | No |
| Requested closing date | 45 days | 30 days | 14 days |
| Earnest money deposit | $4,250 | $8,400 | $10,000 |
| Requested repairs/credits | $8,000 | $3,000 | None |
This visual breakdown reveals the real story. Offer A looks highest but carries the most risk and repair requests. Offer C is lower but closes in two weeks with zero contingencies and no repair negotiations.
Quantify the value of closing speed and certainty
Faster closing and fewer contingencies have real financial value:
- Days on market matter: Every week your home stays listed costs you carrying costs (property taxes, insurance, utilities). If you’re paying carrying costs, a faster close saves you money and lets you move forward with your next purchase sooner.
- Appraisal risk: If your home appraises low, a buyer with an appraisal contingency can renegotiate or withdraw. A cash offer eliminates this risk entirely.
- Inspection leverage: Buyers often use inspection contingencies to request credits for minor issues they knew about when making the offer. A clean offer avoids this back-and-forth.
Evaluate buyer financing strength
Not all financing is equal. Ask your real estate professional to verify the buyer’s financial position:
- Pre-approval letter: Confirms the buyer has been vetted by a lender. Pre-approval is stronger than pre-qualification.
- Cash offer: Eliminates financing risk entirely. Cash buyers close faster and rarely renegotiate.
- Loan-to-value ratio: A buyer putting down 20% or more is less likely to back out if the appraisal is low.
- Debt-to-income ratio: Your agent may learn whether the buyer’s debt load is manageable. High debt increases default risk.
A pre-approved buyer with 20% down and no contingencies is far more reliable than a buyer with a contingency and only 5% down.
Negotiate strategically using offer comparison
When you receive multiple offers, use the comparison to negotiate:
- If the highest offer is contingent: Counter with a request to remove the appraisal contingency or shorten the inspection period. This reduces your risk without lowering price.
- If a lower offer is cleaner: Consider accepting it if the certainty and speed justify the lower price. Calculate the net benefit of closing 15 days sooner.
- If repair requests are excessive: Counter by offering a credit instead of repairs. This gives the buyer flexibility while protecting you from contractor surprises.
- If closing date is too far out: Counter with an earlier date. Faster closing reduces carrying costs and uncertainty.
Your real estate professional should help craft counteroffers that address your priorities. If price is most important, push back on contingencies. If speed matters, accept a slightly lower price for a quick, clean close.
Document all offer terms in writing
Ensure your purchase agreement clearly specifies:
- Exact closing date and any flexibility
- Which party pays for inspections, appraisals, and title insurance
- Repair requests and credit amounts
- Earnest money deposit amount and timeline
- Contingency removal dates
- Walk-through inspection timing
Ambiguity creates disputes. Clear terms protect both parties and prevent last-minute surprises.
Calculate Your Net Proceeds After Selling Costs
Your net proceeds are what you actually take home after selling costs. This is what really matters, not the sale price alone.
Selling costs typically include:
- Real estate agent commission
- Title insurance and closing costs
- Property transfer taxes
- Home inspection and appraisal fees
- Attorney fees (if required)
- Any outstanding mortgage balance
These costs add up quickly. Understanding this helps you set realistic expectations and price strategically.
Use a net proceeds calculator to estimate your take-home amount. Factor in your mortgage payoff, any liens, and all anticipated closing costs. This gives you a clear picture of your financial outcome.
Discuss closing costs with your real estate professional early. Some costs are negotiable. Understanding the full picture helps you make informed decisions about pricing and negotiation strategy.
Selling your home for maximum value requires planning, preparation, and professional guidance. Start by pricing competitively based on local market data. Make strategic improvements that deliver strong returns. Stage your home to help buyers envision themselves living there. Then work with a trusted professional to market effectively and negotiate strong terms.
At CT Heritage Village, we understand that selling a family home is a significant life transition. Andrew Walker’s expertise in local market conditions and personalized selling strategies helps homeowners in Southbury. Whether you’re downsizing to our active community or relocating elsewhere, we’re here to guide you through the process. Request a showing to learn how our team can support your next chapter.
Frequently Asked Questions
What’s the best way to price my home when selling your home for maximum value?
Start by researching comparable sales (homes similar in size, condition, and location sold in the past 3-6 months) and obtain a professional appraisal or comparative market analysis from a real estate professional. Price too high and you’ll sit on the market; too low and you leave money on the table. A skilled real estate advisor can analyze local market conditions, buyer demand, and days on market for similar homes to recommend a competitive listing price that attracts qualified buyers while maximizing your sale price.
Should I make repairs and upgrades before selling, or sell my house as is?
Focus on high-return improvements: fresh paint, minor repairs, deep cleaning, and curb appeal enhancements typically deliver strong ROI. Major renovations (full kitchen remodels, bathroom overhauls) often don’t return their full cost. If repairs are significant and you’re budget-conscious, selling as is and letting the buyer handle them may make sense, though expect a lower offer. A pre-listing inspection helps you identify critical issues and decide strategically based on your timeline and financial goals.
How does home staging help me sell for more money?
Home staging helps buyers picture themselves in your space by decluttering, depersonalizing, and arranging furniture to highlight the home’s best features. Professional photography of a staged home attracts more qualified buyers online. Focus on neutral colors, minimal personal items, and clean, open spaces that make rooms feel larger and more appealing.
What selling costs should I account for in my net proceeds?
Typical selling costs include real estate agent commission, title insurance, closing costs, and any outstanding mortgage payoff. Some sellers also cover buyer closing costs as a negotiation tactic. Use a net-proceeds calculator with your real estate advisor to understand exactly how much you’ll take home after all expenses. This prevents surprises at closing and helps you set realistic pricing expectations.